
AXIS Capital currently trades at $97.37 per share and has shown little upside over the past six months, posting a small loss of 2%. The stock also fell short of the S&P 500’s 12% gain during that period.
Is there a buying opportunity in AXIS Capital, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is AXIS Capital Not Exciting?
We’re passing on AXIS Capital for now. Here are three reasons why there are better opportunities than AXS, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
In general, insurance companies earn revenue from three primary sources. The first is the core insurance business itself, often called underwriting and represented in the income statement as premiums earned. The second source is investment income from investing the “float” (premiums collected upfront not yet paid out as claims) in assets such as fixed-income assets and equities. The third is fees from various sources such as policy administration, annuities, or other value-added services.
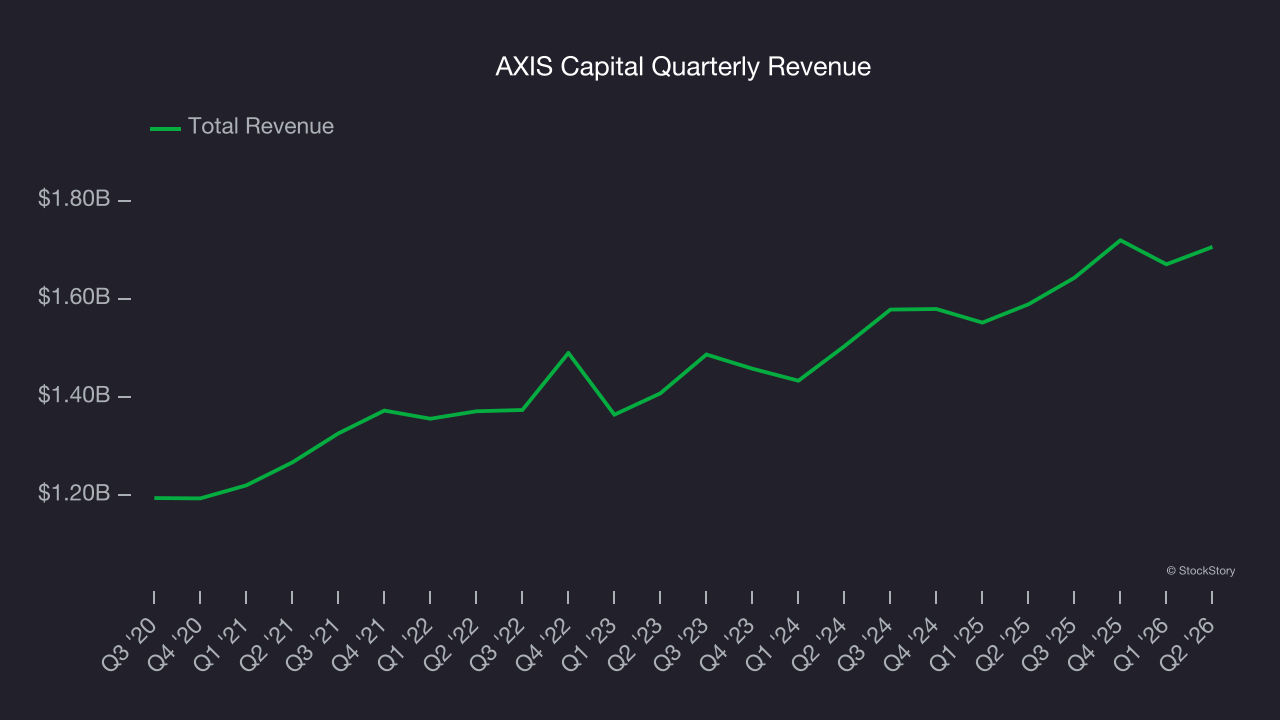
Regrettably, AXIS Capital’s revenue grew at a mediocre 6.7% compounded annual growth rate over the last five years. This fell short of our benchmark for the insurance sector.
2. Net Premiums Earned Point to Soft Demand
When insurers sell policies, they protect themselves from extremely large losses or an outsized accumulation of losses with reinsurance (insurance for insurance companies). Net premiums earned are therefore gross premiums less what’s ceded to reinsurers as a risk mitigation and transfer strategy.
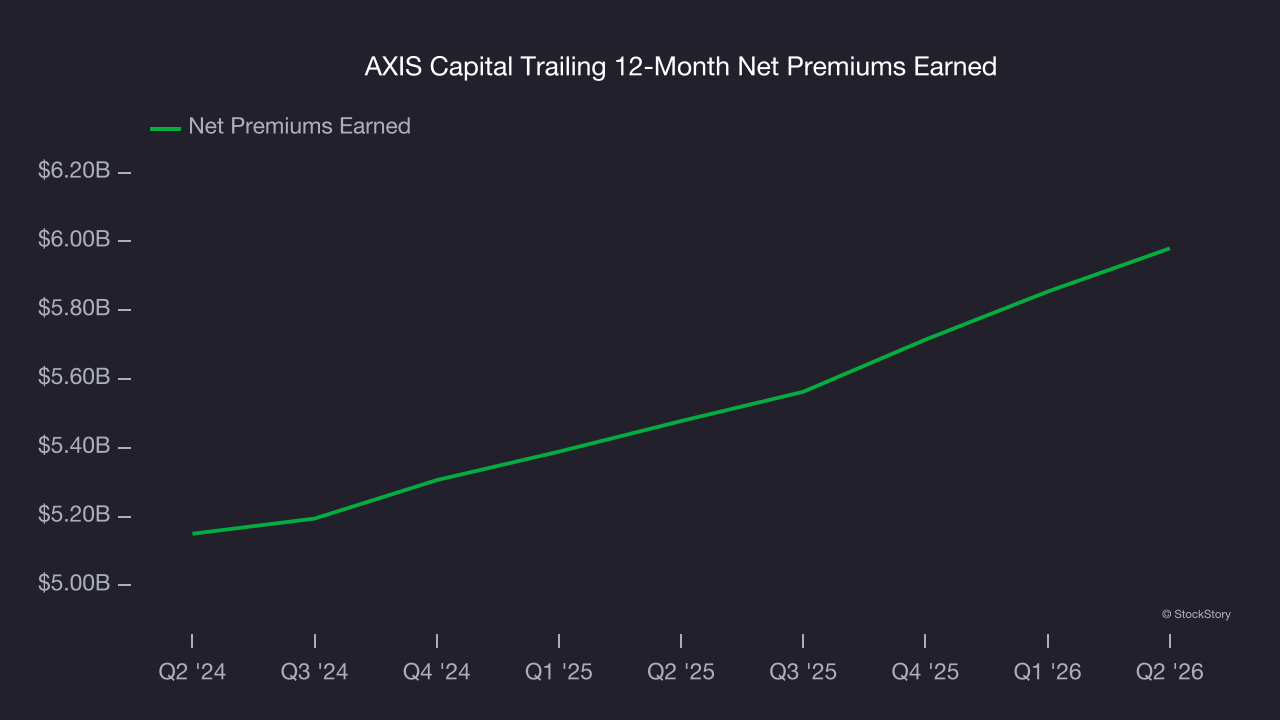
AXIS Capital’s net premiums earned has grown at a 6.1% annualized rate over the last five years, slightly worse than the broader insurance industry and in line with its total revenue.
3. Recent EPS Growth Below Our Standards
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
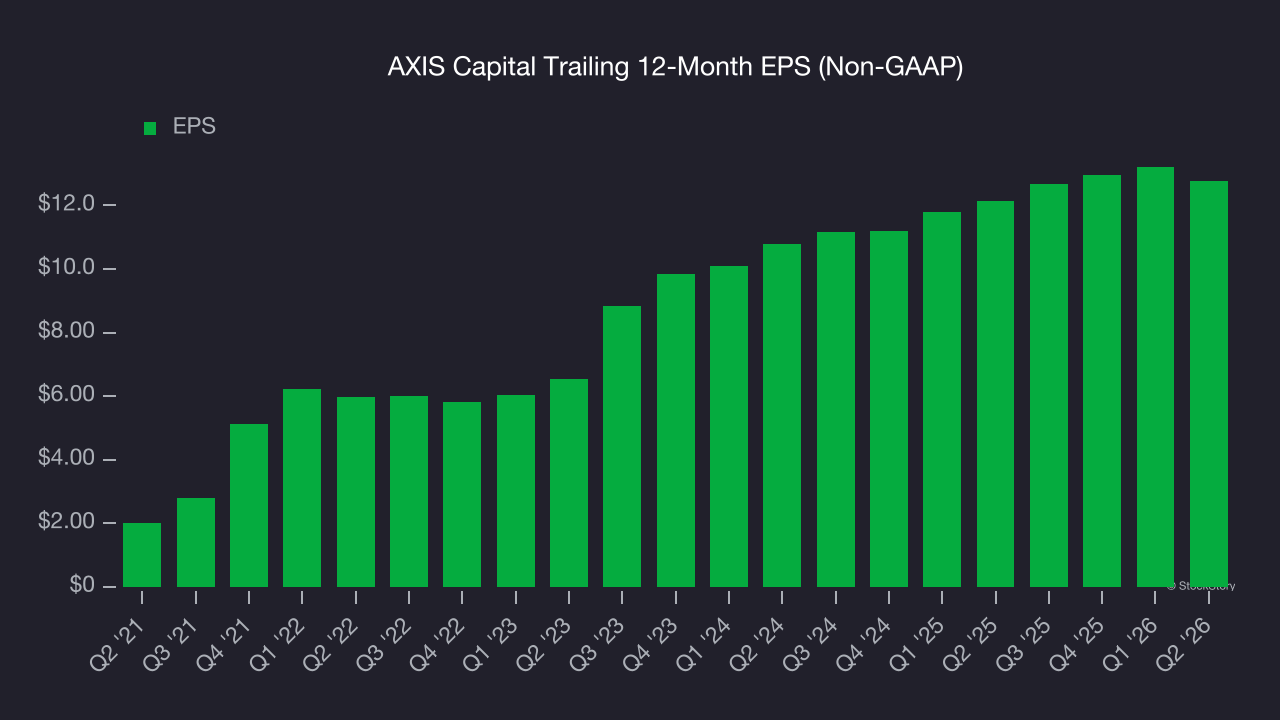
AXIS Capital’s weak 8.8% annual EPS growth over the last two years aligns with its revenue trend. On the bright side, this tells us its incremental sales were profitable.
Final Judgment
AXIS Capital isn’t a terrible business, but it doesn’t pass our bar. With its shares trailing the market in recent months, the stock trades at 1.2× forward P/B (or $97.37 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re pretty confident there are superior stocks to buy right now. We’d recommend looking at our favorite semiconductor picks and shovels play.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.